Mining
Kazakhstan Plans to Double Copper Output by 2030
November 19, 2026

3
Min

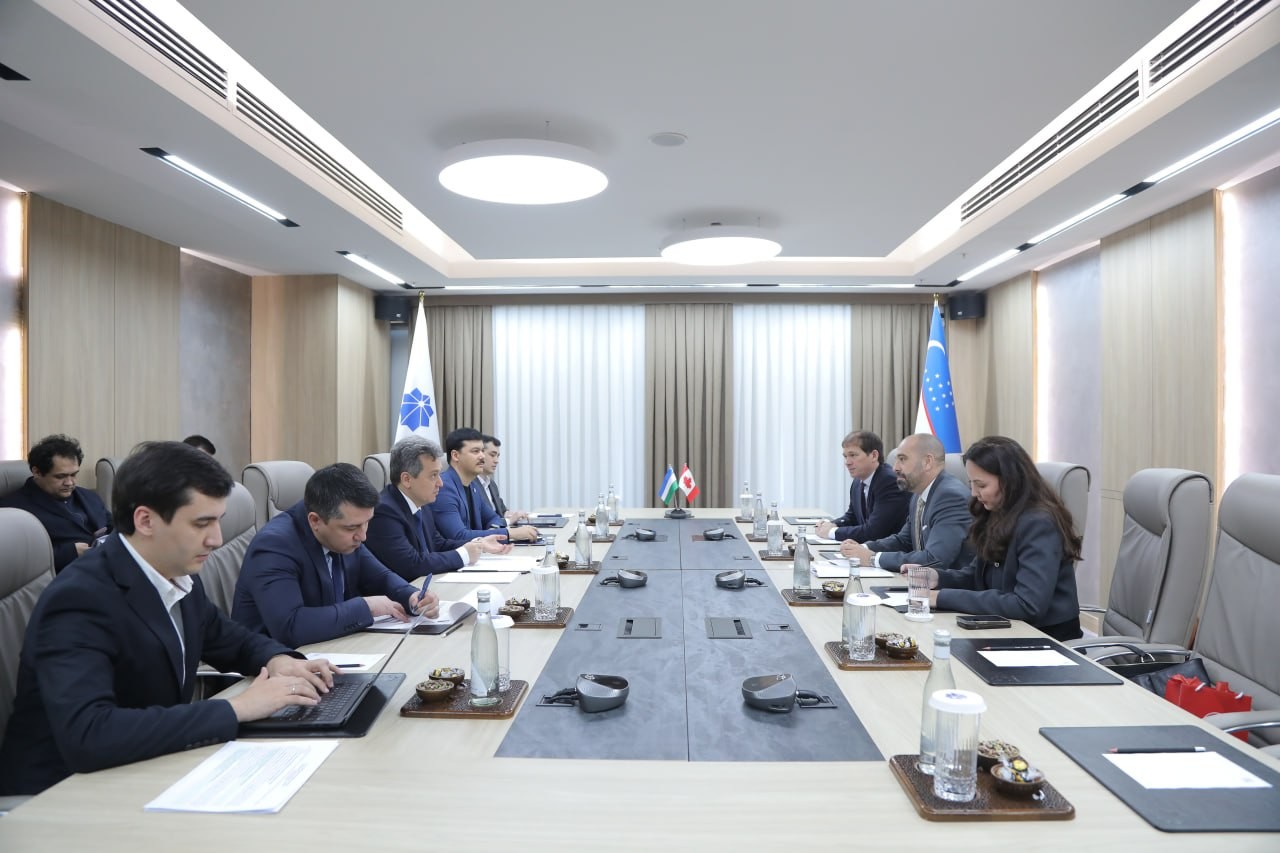
Kazakhstan plans to double its copper production by 2030 and to keep far more of its concentrate at home, Industry and Construction Minister Yersayin Nagaspayev told a government session chaired by Prime Minister Olzhas Bektenov on 17 November, according to the Prime Minister's official information service.
The centrepiece is two new copper smelters, at Balkhash and Aktogay, each with a capacity of 300,000 tonnes. Together with the Koksay and Aidarly projects, which are expected to add 1.7 million tonnes of copper concentrate, they underpin a 2030 target of 1.5 times more concentrate and twice as much copper. Finished copper products are meant to more than double, to 40,000 tonnes, as the same release puts it.
The starting point is a gap between mining and metal. Kazakhstan produces about 3.4 million tonnes of copper concentrate a year but processes only about 59% of it domestically, the government said. The remainder leaves the country as an intermediate product, and the value added in refining goes with it.
Trend reported on 17 November, citing the ministry's press service, that draft amendments would introduce state regulation of tariffs to encourage domestic processing. Nagaspayev also said further localisation requires full production chains inside Kazakhstan. The detail of the tariff mechanism was not published in the material we reviewed.
Kazakhstanskaya Pravda, in an undated report on a government meeting chaired by Bektenov, described a smelter project in the Abai region with capacity of up to 300,000 tonnes of cathode copper a year, investment of $1.5bn and more than 1,000 permanent jobs, fed by concentrate from Bozshakol, Aktogay and Vostokcvetmet. It was said to be on the Unified Industrialisation Map, with infrastructure connections under way. The 17 November summary does not say whether the planned smelters include that project or are additional capacity, a point investors will want clarified.
Two figures in the plan sit uneasily together. Smelters of 300,000 tonnes each imply processing capacity far above the 40,000 tonnes of finished products targeted, so the two numbers may measure different stages of the chain (refined metal versus fabricated goods). The published summaries do not break this down, and readers should treat the 2030 end-state as a headline target rather than a schedule.
The policy logic is clear. A producer that ships concentrate captures only part of the copper price, while a smelter, a refinery and downstream fabrication hold more of the margin and the jobs. Tariff regulation is the stick that would make domestic processing more attractive than export, and it will matter to the miners whose output feeds the new plants.
The wider mining backdrop is mixed. Trend, citing Bureau of National Statistics data, reported on 19 November that gold-bearing ore output rose 12.4% to 34.58 million tonnes in January to October 2026, while gold-bearing concentrate fell 18% to 221,100 tonnes. Metal ore mining, covering 70 enterprises and facilities, produced 6.427 trillion tenge of output, up 1.7% in physical volume.
Sources: Prime Minister of Kazakhstan, 17 November 2026; Trend, 17 November 2026; Kazakhstanskaya Pravda; Trend, 19 November 2026
Image: Caucasus Business Journal archive, via caucasusbusinessjournal.com